Opinion piece by James Leckie
Most limited company directors know about the obvious business expenses.
Accountancy fees, software subscriptions, business travel, and office equipment are unlikely to surprise you.
But a company can legitimately pay, or reimburse a director for, several other costs without creating the tax bill you might expect.
As always with company expenses, the detail matters. An expense being paid from the company bank account does not automatically make it tax deductible, and some benefits have very specific conditions attached to them.
Here are seven worth knowing about.
1. Your mobile phone – including private calls
A limited company can provide a director or employee with one mobile phone or SIM card without creating a taxable benefit, provided the contract is between the company and the supplier.
There is no requirement to separate out private calls. The exemption can cover the handset, line rental and the cost of personal use as well as business calls.
The important distinction is who owns the contract.
If the mobile contract is in your own name and the company simply pays or reimburses your monthly bill, the same exemption does not apply. A second company-provided phone can also fall outside the exemption.
For many owner-managed companies, it therefore makes sense to put the next mobile contract directly into the company’s name.
HMRC guidance: https://www.gov.uk/expenses-and-benefits-mobile-phones/whats-exempt
2. Small gifts to yourself
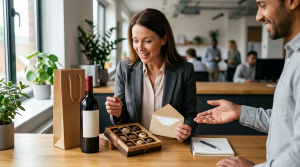
This is one of the more unusual tax exemptions available to directors.
Under the trivial benefits rules, your company can provide a benefit costing £50 or less, including VAT, without Income Tax or National Insurance becoming due, provided it is not cash or a cash voucher, is not a reward for your work and is not something you are contractually entitled to receive.
For directors of close companies – which includes most small owner-managed limited companies – there is an additional £300 annual limit. That limit also applies to qualifying trivial benefits provided to members of the director’s family or household.
So, for example, the company might buy you a £40 bottle of wine, a restaurant voucher or another non-cash gift simply because it feels like it.
It cannot, however, be dressed up as a bonus for completing a project or hitting a target. And if an individual benefit costs £51, it does not qualify at all – you cannot simply claim the first £50.
Michael McCullion of Bright Ideas Accountancy says:
“Trivial benefits are a good example of a perfectly legitimate tax exemption which many small company directors simply never use. The rules are quite prescriptive, though. Keep each benefit within the £50 limit, don’t link it to performance and keep a record of what the company has provided during the tax year.”
3. An annual Christmas party – even if there are only one or two of you
The annual staff event exemption is not limited to businesses with a large workforce.
A small limited company can potentially pay for an annual Christmas party, summer event or similar function without creating a benefit-in-kind charge.
The event must be annual in nature, open to all employees – or all employees at a particular location – and the cost must be £150 or less per head.
The calculation includes VAT and associated costs such as transport and accommodation. Guests attending the event are also included when calculating the cost per head.
The £150 figure is an exemption rather than an allowance. If a particular event falls outside the exemption, the full cost can become taxable rather than just the amount above £150.
Companies can also hold more than one annual event, provided the total cost of the events being treated as exempt does not exceed £150 per head.
For a husband-and-wife company where both spouses are employees, this is one of those expenses that can easily be overlooked.
4. Eye tests – and sometimes glasses
If you spend most of your working day staring at a screen, your company may be able to meet the cost of an eyesight test without creating a taxable benefit.
The exemption applies to qualifying eye tests for employees who habitually use display screen equipment.
The company can also meet the cost of glasses or contact lenses where they are required specifically for screen work.
That does not mean you can put an ordinary pair of everyday designer glasses through the company simply because you sometimes wear them at your desk. The corrective appliance needs to be specifically required for display-screen use.
There was also a useful rule change from 6 April 2026.
Previously, the tax exemption generally relied on the employer providing the qualifying eye test or corrective appliance directly. From 6 April 2026, the exemption was extended so that employers can also reimburse employees for qualifying eye tests and special corrective appliances.
That is particularly useful for directors of small companies who simply arrange and pay for the appointment themselves.
5. Courses which improve the skills you use in your business
Training is another area where directors can sometimes be unnecessarily cautious.
The company can normally pay for work-related training which improves or develops skills relevant to your current employment, or a related role you are likely to perform for the company.
That might include technical training, professional courses, management or leadership development, or training in software that you use in the business.
The exemption can also extend to associated costs such as course materials, examination fees and qualifying travel and subsistence.
The key is the connection with your work.
Paying through the company for a completely unrelated course pursued mainly as a hobby or as preparation for an entirely different career is a different matter.
6. Pension contributions paid directly by your company
Many directors know that they can contribute personally to a pension, but company contributions can be particularly useful.
An employer contribution made by the company into a director’s registered pension scheme will normally be deductible when calculating company profits, provided it is incurred wholly and exclusively for the purposes of the trade.
Unlike a personal contribution, the money is paid directly by the company rather than first having to be extracted as salary or dividends.
Employer pension contributions are also not normally treated as a benefit in kind.
There are still pension tax rules to consider, including the annual allowance and potentially carry forward. Particular care can also be worthwhile with very large one-off contributions, especially where the amount appears out of line with the director’s duties or overall remuneration package.
Corporation Tax relief is normally given for the accounting period in which the contribution is actually paid.
7. Income protection for a company director
Income protection is another expense many company directors assume they have to arrange and pay for personally.
That is not necessarily the case.
A limited company can arrange an executive income protection policy for a director or employee. Instead of you paying the premiums from your personal post-tax income, the company takes out the policy and pays the premiums.
The purpose of the cover is straightforward: if illness or injury prevents the insured person from working for an extended period, the policy can provide the company with a regular benefit.
The company can then use those funds to continue paying the director or employee, subject to the terms of the policy and the normal payroll and tax treatment of any amounts subsequently paid to them.
This can be particularly relevant for small limited company owners whose personal income depends heavily on their ability to continue working. A long period away from the business can affect both the director personally and the company’s ability to generate revenue.
The tax treatment is different from simply buying a personal income protection policy and paying for it from the company bank account. The policy needs to be structured correctly as employer-provided cover, and the precise treatment will depend on the arrangement.
David Townsend of Income Protection Help says:
“Directors often protect their homes, cars and businesses but overlook the thing that makes all of those possible – their income. Executive income protection lets a limited company put cover in place for a director or employee rather than leaving them to fund a personal policy from income they have already paid tax on.”
For directors comparing the options, it is therefore worth distinguishing between personal income protection and a policy specifically designed to be arranged and funded by a limited company.
Don’t assume that ‘personal’ automatically means disallowed
A sensible principle underlies most of these rules.
A limited company is an employer as well as a business, so some expenditure which benefits you personally can still fall within specific employee tax exemptions or legitimate employer-provided arrangements.
That does not mean anything vaguely connected with work can be put through the company.
The safest approach is to distinguish between genuine business expenditure, exempt employee benefits and ordinary personal spending.
Small details can completely change the tax treatment – whether the mobile contract is in the company’s name, whether a gift was linked to performance, whether a staff event was open to everyone, or whether an insurance policy has been structured as employer-provided cover.
When in doubt, check the precise conditions or ask your accountant before putting the cost through the business.
Author bio:
James Leckie is an economics graduate who worked in finance and business analysis roles before founding a series of popular business news sites. He is the editor of ITContracting.com and ByteStart.co.uk and has been publishing expert content on contracting, tax, and small business issues since 1999. Connect with James via LinkedIn.
Author Profile

- Always on the chase after hot and trending London and UK business news that disrupt, inform and inspire.
Latest entries
 Business Innovation NewsOctober 1, 2026Morus Art Group launches in London with Out Of The Blue Exhibition
 Business SpotlightSeptember 29, 20267 Things you might not realise your Limited Company can pay for
 Business SpotlightSeptember 29, 2026How a New Relevant Life Insurance Website Supports UK Limited Company Directors
 Business Innovation NewsAugust 28, 2026IFB brings the Search for regulated financial Companies to Mobile